All Categories
Featured
Best Medigap Plans
Nationwide also gives you the ability to essentially buy additional upside prospective with their "High-Cap" or "High-Par" Indexed Universal Life insurance coverage financial investment strategies, which include an extra 1%-2% cost. This reduces an IUL's flooring below 0%, there may be years when you want the extra upside potential. Diverse Set of IUL Crediting StrategiesUnique Multi-Index StrategyHistory of Caring For Inforce Policyholders FairlyLarge Size, Mutuality, and Solid Financial StrengthStrong concentrate on Volatility Control IndexesGood long-lasting growth, however lackluster early money valuesParticipating policy loan rate is capped to be no greater than 8% Columbus Life Insurance Coverage is the IUL arm of the well-rated insurance conglomerate of Western Southern Group, which entered the IUL arms race in the middle of the last years.
Because their only responsibility as a company is to the long-term responsibility of policyholders, they are more likely to do right by their inforce block of organization. This can be plainly seen in this screenshot we recently sent out to among our customers revealing how Columbus Life's IUL cap rates have actually steadily increased from 8.75% in December 2022 to 10% exactly one year later as rates ticked up.

The worst IUL companies continuously declare to have the very best Indexed Universal Life insurance policy with the highest cap. However, they'll start with a very high cap to capture market share, then quickly pull the rug out from under their clients once they shelve that item and start a new one.
That method, policyholders obtaining for outdoors financial investment opportunities still had the prospective to earn at least some positive arbitrage. Solid S&P 500 cap rateParticipating loan rate is capped at 6% (but has been lower for a while)Their documented history of dealing with in-force insurance policy holders fairlyMutual Holding Business without any outdoors stockholdersTheir uncapped indexed account is currently unsightly and inactionable.
To clarify, all the very best IUL companies in this article use some sort of free chronic illness rider, but National Life Group's is perhaps the most robust. I also wish to mention that I am specifically discussing their "Peak Life" product, which is their "larger case" item using a more structured fee structure.
Protecting Financial Wealth with Term Life Insurance
Technically the rider is "complimentary", however we have actually found when stress-testing fees that the death expenditures are a bit higher than other of the very best IUL companies. This is to be expected, and you might have heard me state, "There's rarely any deals in insurance. Whatever gets priced completely rather quickly."That stated, National Life Group remains in the running for the finest Indexed Universal Life insurance business for customers trying to find a balance of efficiency, earnings, and comprehensive defense.
Insurance in San Diego CADon't invest excessive time on these details as your numbers will definitely differ, but this shows the type of chronic disease rider payments they provide. to discover which are presently the very best IUL policies with robust Persistent Illness Riders and solid IUL crediting methods for tax-free earnings if you do not become too ill or injured to work separately.
Indexed Universal Life Insurance has numerous moving parts at its core, not to point out all the prospective bells and whistles various companies add to their policies. Don't simply fall for a good story and slick sales pitch. now that you understand what to ask. If you're weighing IUL versus your existing retirement accounts, our complete breakdown of covers the crucial distinctions in contribution limits, tax treatment, and flexibility.
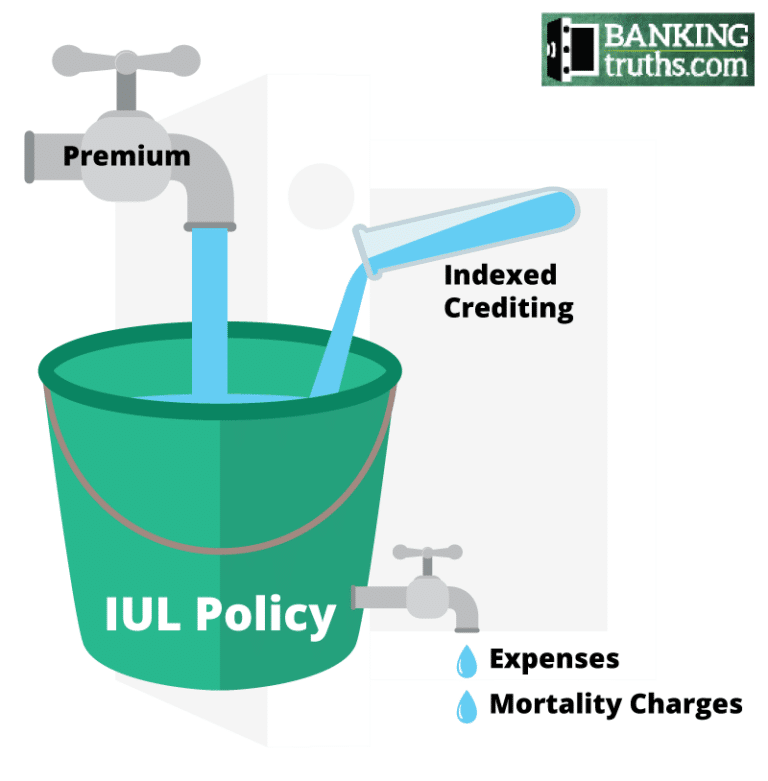
Throughout the majority of the 1900s the only life insurance coverage items were Whole Life and Term. Term insurance offered lower expenses for short-lived life insurance coverage. Whole Life provided a guaranteed death advantage for an ensured level premium, however likewise had an attached cost savings part with an ensured irreversible development rate in addition to non-guaranteed dividends.
Insurance in San Diego CABest Medigap Plans
The concept with Universal Life is that the growth of the savings account will lower the amount of pure insurance in the policy, which would bring down the rising cost per system of death advantage. In 1986, soon after the meteoric rise of Universal Life, life insurance coverage business had the concept of adding an investment component.
This caused the IRS limiting how much premium anyone could pump into any quantity of irreversible survivor benefit for future tax-free retirement earnings. Regardless, as the stock market raved on throughout the 1990s, VUL ended up being the insurance coverage product of choice for cash accumulation. In 1997, the very first Indexed Universal Life item was created by TransAmerica (not on the list of 2026 Best IUL companies). Initially, Indexed Universal Life insurance coverage didn't make a huge splash at all.

Latest Posts
Exploring 2026 Individual Health Trends in Eastvale
Everything You Need to Know About Medicare

Comparing PPO and HMO Costs for Santee